Browse this answer and all topics
More of my clients now show up to our first call with a screenshot from ChatGPT. Some of those answers are solid. Some are off in ways that matter, like an old program rule or a down payment minimum that doesn't fit their situation. I've watched AI tell people they can't buy when they can, and tell people they can when they can't.
I'm Jason Kindler. I've been helping Florida families buy, build and refinance since 2001, and I'm the President of First Coast Mortgage Funding. I use AI every day, and I want my clients using it too. They just need to ask it the right questions, and then ask a licensed loan officer the questions AI can't answer. That's what this guide is about.
Have a question about your own situation? Ask Jason Kindler, NMLS #157168. Call or text 904-734-3255, or book a 15-minute call.
What AI is good for when you're buying a home
Used the right way, an AI chat tool is like a patient tutor who never gets tired of "dumb" questions. It's good at:
- Learning the language. Escrow, prepaids, PMI, debt-to-income, Loan Estimate. Ask for one-sentence definitions before your first lender call.
- Mapping the process. Have it walk you through the steps from preapproval to closing, and what you do versus what the lender does at each step.
- Building your question list. This is where AI shines. It can turn a messy conversation into a one-page list of questions to bring to a loan officer.
- Getting organized. Document checklists for W-2, self-employed, retired or military buyers, so you gather paperwork once.
- Understanding forms. It can explain what each section of a Loan Estimate means, as long as you leave your personal information out.
What AI can't do for you
Here's the part most AI answers leave out:
- It can't see your credit report.
- It can't verify your income, assets or the home you want.
- It can't quote a real rate or approve a loan.
- It can be out of date, especially on Florida programs that change during the year.
- It can sound sure and still be wrong.
And one privacy rule I'd put above all the rest: never paste your Social Security number, account numbers or full documents into a chatbot. Use rough ranges instead of exact figures. When it's time for real documents, a licensed lender will give you a secure way to send them.
Programs, guidelines and lender rules change, and two lenders can look at the same file and reach different answers (here's why mortgage decisions differ by lender). AI has no way of knowing which rules apply to your file today. So use it to get smart, then let a pro check the math.
How to write a better mortgage prompt
Vague questions get vague answers. "What loan should I get?" gives the AI nothing to work with. A strong mortgage prompt has six parts:
- Who it should be. Tell it to act as a patient mortgage educator, not a salesperson.
- Who you are. First-time buyer, homeowner, self-employed, veteran, and the Florida city or county you're looking in.
- What you want. Buy, build, refinance or use your equity, and roughly when.
- How you want it. A checklist, a simple table, pros and cons, or a list of questions.
- The guardrail. Tell it not to give you rates or payment amounts. Those need your real file.
- The handoff. Ask it to end with what you should verify with a licensed loan officer.
Then push back with follow-ups like "What's the downside?", "How current is this information?" and "What am I not asking that I should be?" The full fill-in-the-blank template is on page 6 of the free guide.
Sample prompts from Ask AI Before You Apply, by stage
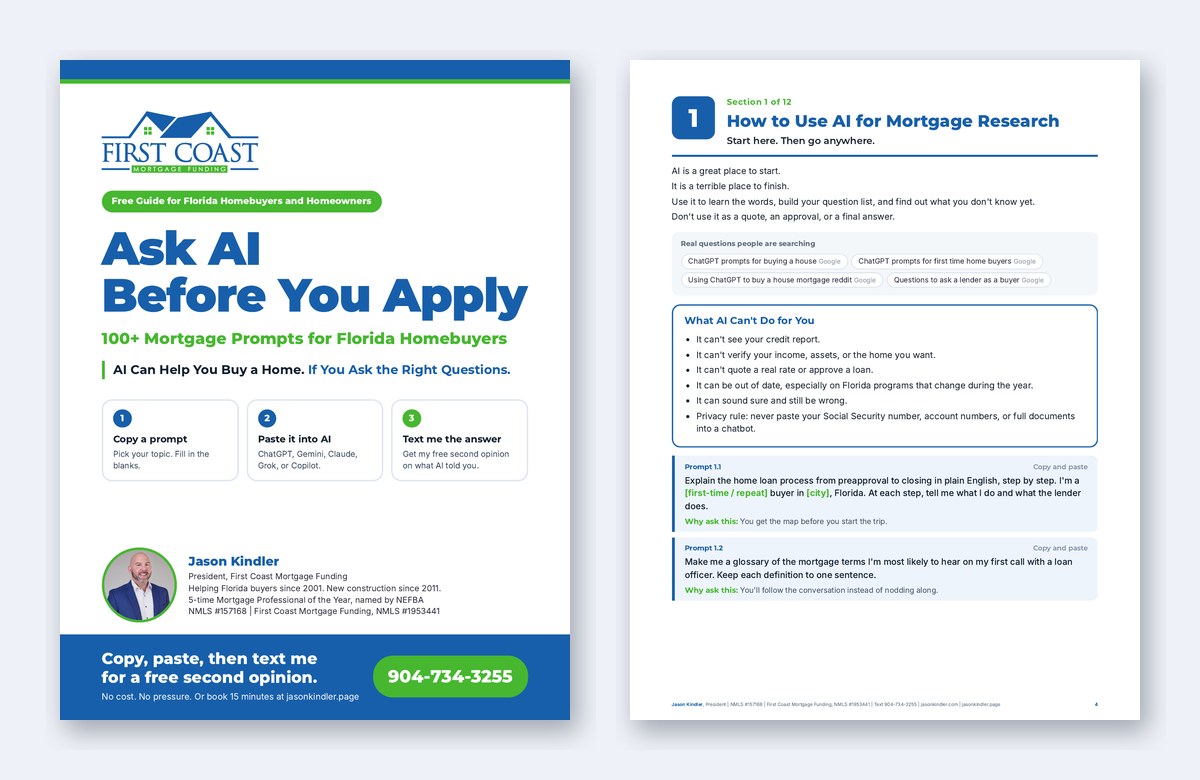
These 8 come straight from the guide. Copy one, replace anything in [brackets] with your details, and paste it into the AI tool you like. The full guide has 100+ prompts and questions across 12 sections.
Stage 1: Before you talk to anyone
Stage 2: Getting your budget and preapproval ready
Lenders don't all use "prequalification" and "preapproval" the same way, so ask what was actually verified. I explain the difference in upfront underwritten preapprovals. For the budget side, see how much house you can afford and debt-to-income ratio explained.
Stage 3: Picking a loan type
When you're ready for the real comparison, read FHA vs. conventional loans in Florida and what credit score you need to buy a house.
Stage 4: Comparing lenders and Loan Estimates
More on that in how to compare two Loan Estimates. If you paste numbers into an AI tool, paste numbers only, never names, addresses or account details.
Questions to ask a mortgage lender (the ones AI can't answer)
AI got you smart. Now ask a human. The best questions to ask a mortgage lender are about your file, not mortgages in general. Two from the guide's "Questions to Ask Your Loan Officer" section:
Other things worth asking any lender before you commit:
- What would make my approval stronger before I make an offer?
- What will my total cash to close look like, including prepaids and escrow?
- How does your rate lock work, and what happens if closing moves?
- Do you offer the Florida Housing programs I might qualify for?
- Will you service my loan, or will it be transferred after closing?
Before you share documents with anyone, look up their license on NMLS Consumer Access. Mine is NMLS #157168, and First Coast Mortgage Funding is NMLS #1953441. A loan officer who gets annoyed by these questions is giving you an answer too.
Questions to ask when buying a house in Florida (beyond the loan)
Florida adds a few questions that national AI answers often skip. Ask AI to explain them, then confirm with your agent, insurance agent and lender:
- Insurance first. How old is the roof, and will the home need a 4-point or wind mitigation inspection? See 4-point and wind mitigation inspections.
- Flood zone. Is the home in a flood zone, and will the lender require flood insurance?
- HOA and CDD fees. What are they, and are they included in my budget?
- Property taxes after the sale. Why might my taxes differ from what the seller paid, and when do I file homestead? See how to file for homestead exemption.
- Cash to close. What will I pay at closing besides my down payment? See Florida closing costs.
- Down payment help. Which Florida programs fit my county and job? First Coast Mortgage Funding offers Florida Housing programs such as Hometown Heroes, FL Assist and HFA Preferred, plus Nassau County SHIP. Program rules and funding change, so confirm the current details. Start with my Florida down payment assistance FAQ.
Get the full guide: 100+ mortgage prompts for Florida homebuyers
Ask AI Before You Apply: AI Can Help You Buy a Home. If You Ask the Right Questions. is a free PDF with 100+ copy-and-paste prompts and questions in 12 sections:
- How to use AI for mortgage research, plus a fill-in prompt template
- Getting ready: credit, budget and documents
- First-time homebuyers
- Loan types: conventional, FHA, VA, USDA and jumbo
- Self-employed and 1099 income
- New construction and one-time close construction loans
- Florida down payment help
- Florida insurance and inspections
- Refinancing and HELOCs
- Comparing lenders and Loan Estimates
- Questions to ask your loan officer
- Red flags
Free second opinion: text me what AI told you
AI gave you an answer, and now you want to know if it's right for you. That's the part AI can't do, and it's the part I do every day.
- Copy the AI answer, or take a screenshot of the part you have questions about.
- Text it to me at 904-734-3255 with one line about your goal: buy, build, refinance or use your equity.
- I'll tell you what's right, what's off and what it means for you. No cost and no pressure.
You can copy this text: "Hi Jason, I'm looking to [buy / build / refinance] in [county]. I asked AI about [topic] and it told me this: [paste answer]. Is that right for me?"
Please don't text your Social Security number, account numbers or full bank statements. Rather talk it through? Book a free 15-minute call at jasonkindler.page. Every loan is subject to approval.
FAQ
Can I use ChatGPT or another AI tool to research a mortgage?
Yes. AI tools are useful for learning mortgage terms, mapping the steps from preapproval to closing and building a list of questions for a loan officer. They can't see your credit, verify your income or approve a loan, so treat what they say as a starting point and confirm it with a licensed loan officer.
Is AI mortgage advice accurate?
Sometimes, but not reliably. AI can be out of date, especially on Florida programs that change during the year, and it can sound sure and still be wrong. Ask it where its information came from and how current it is, then verify anything important with a licensed loan officer.
What questions should I ask a mortgage lender?
Ask questions about your own file: which loan options fit you and why the others were ruled out, what would make your approval stronger, whether your preapproval was reviewed by an underwriter, what your total cash to close will be, how the rate lock works and whether the lender services the loan after closing.
Can AI tell me what mortgage rate I'll get?
No. A real rate depends on your credit, income, assets, the home, the loan type and the day you lock. An AI tool can explain how rates and APR work, but only a lender that has reviewed your information can quote your rate.
What should I never paste into an AI chatbot?
Never paste your Social Security number, date of birth, account numbers or full documents like bank statements and tax returns. Use rough ranges instead of exact figures. When it's time for real documents, use your lender's secure upload.
Can AI tell me if I qualify for Florida down payment assistance?
It can explain how Florida programs work and what to ask, but it can't confirm eligibility or current funding. First Coast Mortgage Funding offers Florida Housing programs, including Hometown Heroes, FL Assist and HFA Preferred, and Nassau County SHIP. Program rules, limits and funding change, so confirm current details with the program or a participating lender.
What's the difference between prequalification and preapproval?
Lenders use the two words differently. What matters is what the lender actually checked. Ask whether your credit, income and assets were verified, and whether an underwriter reviewed the file or the letter is based only on what you told the lender.
How do I check if a loan officer is licensed?
Look them up on NMLS Consumer Access (nmlsconsumeraccess.org). It shows the loan officer's and company's NMLS numbers and the states where they're licensed. Jason Kindler is NMLS #157168, and First Coast Mortgage Funding is NMLS #1953441.
Which AI tools work with these prompts?
The prompts in Ask AI Before You Apply work in any general AI chat tool, including ChatGPT, Gemini, Claude, Grok and Copilot. Replace the parts in brackets with your own details, and leave out personal identifiers.
Is the Ask AI Before You Apply guide free?
Yes. Enter your name and email on this page to download the PDF right away, and a copy is emailed to you too. Phone is optional. The guide is for education and isn't a loan application or a commitment to lend.
Will Jason really review what AI told me?
Yes. Text the AI answer, or a screenshot of it, to Jason at 904-734-3255 with a line about your goal, and he'll tell you what's right, what's off and what it means for you. There's no cost and no obligation. Please don't include Social Security numbers or account numbers.
Jason Kindler | President, NMLS #157168
First Coast Mortgage Funding | Licensed in Florida
jasonkindler.com | Call or text 904-734-3255
Sources: CFPB, What's the difference between a prequalification letter and a preapproval letter? (https://www.consumerfinance.gov/ask-cfpb/whats-the-difference-between-a-prequalification-letter-and-a-preapproval-letter-en-127/); CFPB, Loan Estimate explainer (https://www.consumerfinance.gov/owning-a-home/loan-estimate/); NMLS Consumer Access (https://www.nmlsconsumeraccess.org/); Florida Housing Finance Corporation, Homebuyer Loan Programs (https://www.floridahousing.org/programs/homebuyer-overview-loan-programs/homebuyer-loan-programs). All accessed Nov. 20, 2026.
This article is for educational purposes only and is not a commitment to lend, an offer of credit or a preapproval. It does not quote or advertise any interest rate, APR or payment. AI tools can be wrong, incomplete or out of date. Nothing in this article, the Ask AI Before You Apply guide or any AI answer is a rate quote, a loan approval or a promise of terms. Your options depend on your credit, income, assets, property and program guidelines. Loan programs, guidelines, eligibility and funding change, and down payment assistance is subject to program eligibility and available funding. All loans are subject to credit approval, underwriting, eligibility and property requirements. Not all borrowers will qualify. First Coast Mortgage Funding LLC is not affiliated with Florida Housing Finance Corporation, Nassau County, the VA, FHA, USDA or any government agency. ChatGPT, Gemini, Claude, Grok and Copilot are trademarks of their owners; this article and the guide are not affiliated with or endorsed by them. Jason Kindler, NMLS #157168, licensed in Florida. First Coast Mortgage Funding LLC, NMLS #1953441. 11363 San Jose Blvd Bldg 200, Jacksonville, FL 32223. Licensing details: https://jasonkindler.com/licensing-and-disclosures. Equal Housing Opportunity.